The life policy that holds a fortune, read through UK law
“From clogs to clogs
in three generations”
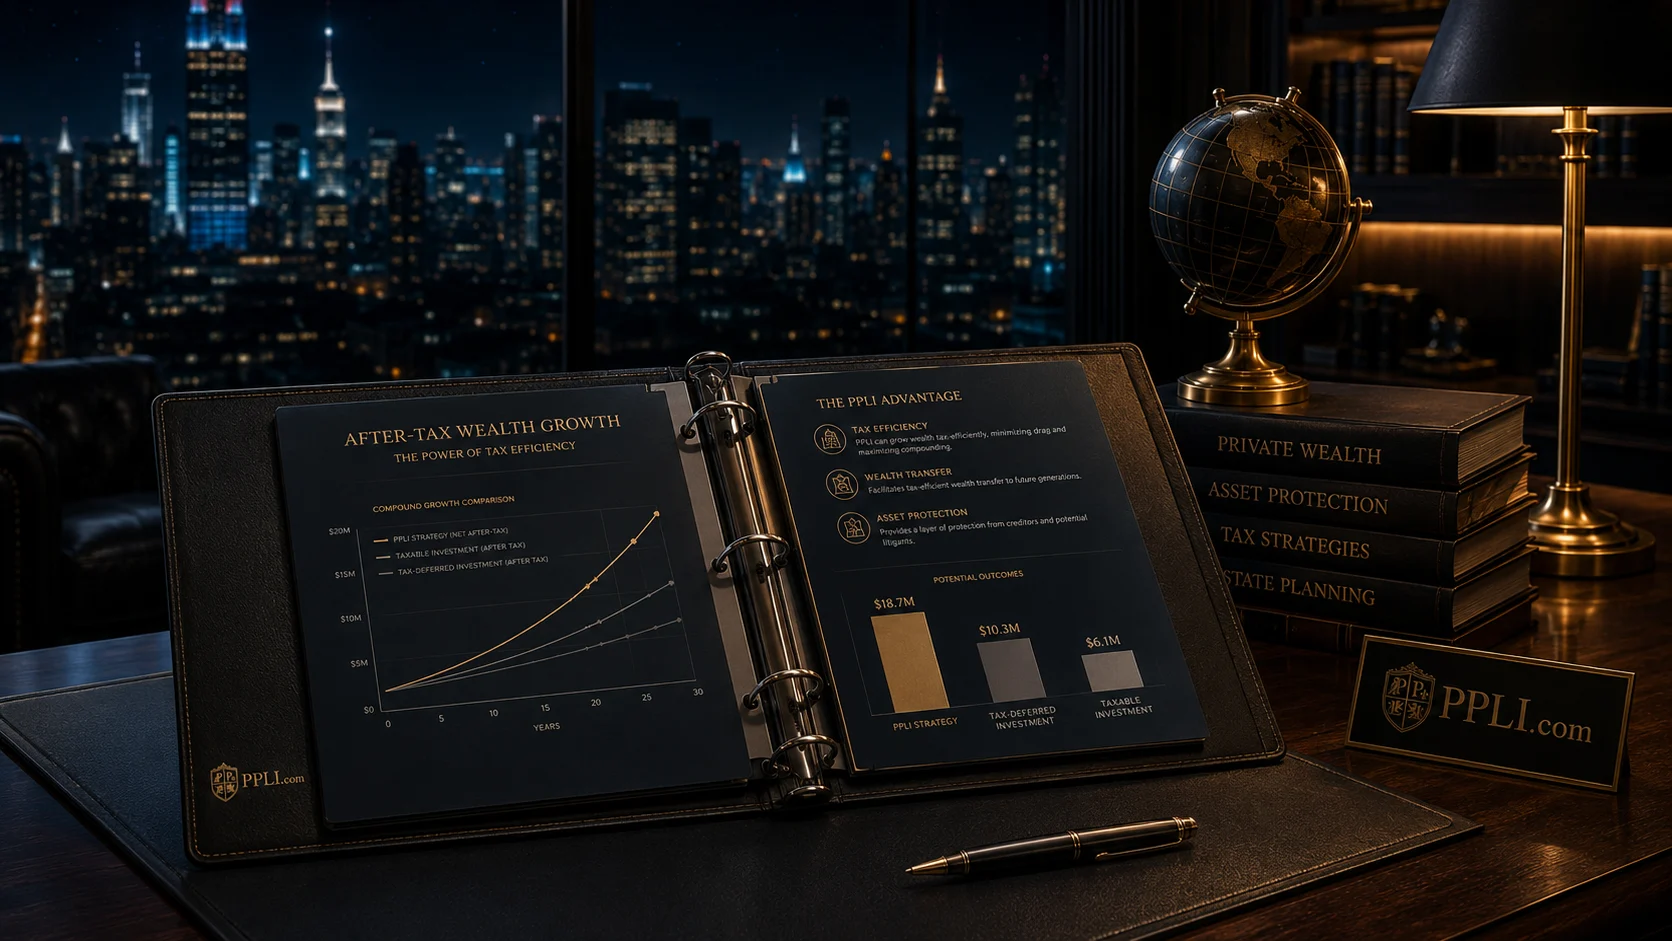
How the policy works
for a UK resident
The full account is on PPLI for UK residents.
Place
Grow
Pass on
Does the UK treatment fit your family?
UK research, with its sources
Five jurisdictions
The Isle of Man and Luxembourg descriptions follow published summaries by local law firms and by Luxembourg for Finance, not the statutes themselves. What each regime pays, and to whom, is in if an offshore life insurer fails. The five are compared side by side on jurisdictions for UK residents.
Questions UK families ask first
What is private placement life insurance for a UK resident?
Is an offshore bond tax-free in the UK?
Can I choose my own investments inside the policy?
Does the policy take my assets out of inheritance tax?
Is my money protected if the insurer fails?
Will HMRC know about the policy?
Written for UK private wealth
UK-resident families
Families arriving or leaving
Advisers and family offices
PPLI.com is not authorised by the Financial Conduct Authority and does not give personal advice. This is general information about UK law, not an invitation or inducement to enter into any insurance or investment contract. Policies issued by insurers outside the UK are not protected by the Financial Services Compensation Scheme.
Sources: ITTOIA 2005 s.484 (chargeable events); s.507 (5% allowance); s.516 and s.520 (personal portfolio bonds); IPTM3650 (15% deemed gain); ITA 2007 s.18(4) (savings income); HS321 (2026) (no basic-rate credit); gov.uk income tax rates; IHTA 1984 s.6A (long-term residence); gov.uk trusts and inheritance tax; FSCS insurance cover; GFSC standard condition for life companies; Central Bank of Ireland, Insurance Compensation Fund; JFSC insurance legislation; IEIM400840 (CRS); TRSM23030 (trust registration).
Begin a private conversation

Editorial standards