Private Placement Life Insurance (PPLI) and foreign life policies for NRIs and Indian families
“A new set of decisionmakers is taking over family wealth, and many of them don’t simply inherit their parents’ arrangements. They want to understand the structure before they buy into the relationship.”
Indian law as at 1 November 2026, Financial Year 2026-27, for an individual who owns the policy personally. Section numbers follow the Income-tax Act 1961; the Income-tax Act 2025 applies from 1 April 2026 and renumbers them. The provisions that decide most answers here: 10(10D) is now section 11 with Schedule II, item 2; 56(2)(xiii) is 92(2)(l); 45(1B) is 67(5); 206C(1G) is 394(1); 6(6) is 6(13). They are set out in the table below; the complete renumbering is on the tax page.
PPLI.com is a research publisher. It is not an insurer, an insurance intermediary or an investment adviser, it is not registered with IRDAI or SEBI, and it does not solicit, arrange or recommend insurance in India. Nothing here is an offer of insurance. A resident of India needs the Reserve Bank’s permission to take a new life policy from an insurer outside India.
Why NRI and cross-border Indian families use a foreign life policy:
tax, FEMA and succession
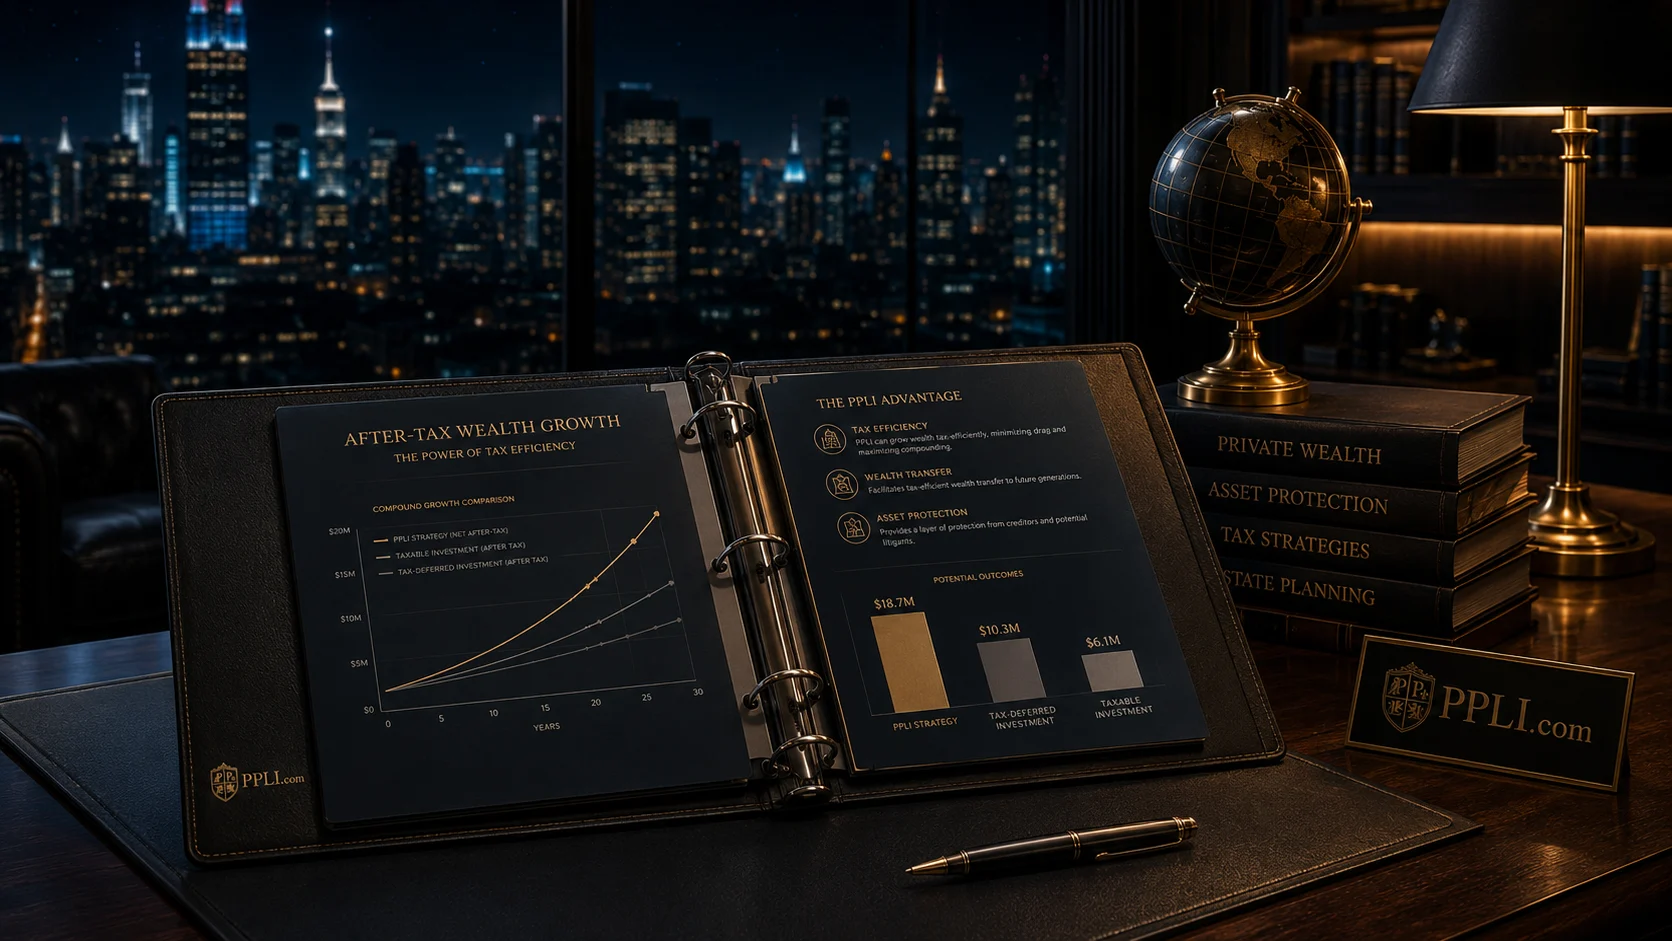
How the policy works
for an NRI family
The full account, with the four Indian rules, is on PPLI under Indian law.
Place
Grow
Pass on
Indian statutory framework for a foreign life policy (FY 2026-27)
| Rule or event | Income-tax Act 1961 / FEMA authority | Income-tax Act 2025 (from 1 April 2026) | How it applies to an NRI, RNOR or resident |
|---|---|---|---|
| Buying and holding a foreign life policy (FEMA) | FEMA 12(R)/2015-RB, regulations 4 and 4(ii); RBI Master Direction on LRS | FEMA 12(R)/2015-RB continues to govern | An NRI may buy a foreign policy from foreign income: FEMA does not reach it, so there is no RBI permission, LRS limit or TCS. A policy bought while non-resident may be kept after return under regulation 4(ii). A resident of India needs the RBI’s prior permission for a new foreign policy, and life premium is not a permitted LRS purpose. |
| Exemption ceiling on maturity and surrender | Section 10(10D) | Section 11 read with Schedule II, item 2 | Money received in life is exempt only if the annual premium stays within ₹2.5 lakh for a ULIP issued on or after 1 February 2021, or ₹5 lakh for another policy issued on or after 1 April 2023, and within 10% of the sum assured. A PPLI premium is above both ceilings. |
| Surrender or partial withdrawal in life | Section 56(2)(xiii) for a non-ULIP; section 45(1B) for a ULIP | Section 92(2)(l) for a non-ULIP; section 67(5) for a ULIP | Growth inside the policy is not taxed year by year while nothing is received. For an ordinarily resident holder, the amount received less premiums is income from other sources at slab rate if the contract is a non-ULIP, and a capital gain if it is classified as a ULIP. Have your CA classify the contract in writing. |
| Death benefit | Section 10(10D), eighth proviso | Section 11 read with Schedule II, item 2 | The sum received on the death of the insured is exempt whatever the premium. It is paid by the insurer to the named nominee or trust, outside Indian probate. India has no estate duty. |
| Returning NRI: the RNOR window | Section 6(6) read with section 5 | Section 6(13) read with section 5 | A returning NRI who qualifies as resident but not ordinarily resident, usually for two to three financial years, is not taxed in India on policy money that arises and is received outside India, and does not file Schedule FA in those years. |
| Reporting, TCS and FAST-DS 2026 | Schedule FA (ITR-2 and ITR-3); Black Money Act 2015; section 206C(1G); Finance Act 2026 and FAST-DS Rules 2026, G.S.R. 732(E) of 14 August 2026 | Schedule FA; section 394(1) for TCS; FAST-DS Rules 2026 | Every resident and ordinarily resident holder reports the policy in Schedule FA each year, and the insurer’s country reports it to India under CRS. A policy bought with NRI earnings and never listed after return can be declared under FAST-DS 2026 between 16 August and 31 December 2026, for a fee of ₹1 lakh where such assets total up to ₹5 crore. |
Position as at 1 November 2026, for an individual who owns the policy personally. Sources: the Income Tax Department’s text of both Acts, the RBI’s FEMA notifications and LRS Master Direction, the Memorandum to the Finance Bill 2025 and the FAST-DS Rules 2026. The working is on how India taxes a foreign policy, section 10(10D) explained, FEMA, LRS and foreign insurance and FAST-DS 2026.
Where do you stand?
What Indian law says
India taxes a non-resident only on Indian income, and FEMA does not govern your foreign earnings. A policy bought abroad from foreign income needs no RBI permission, no LRS and no TCS, and it is outside Schedule FA while you are non-resident.
What a policy changes
While you stay abroad, the policy’s meaning depends on your host country: nothing to defer in the UAE or Singapore, a chargeable-event regime in the UK, section 7702 and PFIC questions in the US. Its Indian meaning begins the day you decide to come home.
The catch
If you fund the policy from a Dubai or Singapore account and later return, keep the source documents. Schedule FA, CRS and, if a year is missed, FAST-DS will all ask where the premiums came from.
Basis: Income-tax Act sections 5 and 6; FEMA 12(R) regulation 4(ii).
Offshore PPLI, GIFT City policy or Indian ULIP: three structures compared
| Feature | Offshore PPLI (Singapore, Luxembourg, Ireland, Bermuda, Cayman) | GIFT City IFSC policy (IFSCA IIO) | Domestic Indian ULIP (IRDAI) |
|---|---|---|---|
| Currency and custody | USD, EUR or another currency; the assets sit in a separate account held for the policy by a custodian | USD, and now multi-currency plans; the money sits in the insurer’s own funds | Rupee; the money sits in the insurer’s unit-linked funds |
| Who can buy | An NRI, from foreign income, without RBI permission; the policy may be kept after return under regulation 4(ii). A resident needs RBI permission under regulation 4 | NRIs and foreign nationals. IFSCA says residents may pay under LRS, but FEMA regulation 4 has not been amended: treat the resident route as unresolved and get the bank’s confirmation in writing | Generally open to residents |
| Investment mandate | A separately managed account; the family chooses the strategy and the manager within the insurer’s approved list | The insurer’s fund menu | The insurer’s funds, with switches inside that menu and a five-year lock-in |
| Indian tax on surrender | No exemption at PPLI scale. Non-ULIP: slab rate under section 56(2)(xiii), now 92(2)(l). If classified as a ULIP: capital gain under section 45(1B), now 67(5) | Exempt under section 10(10D) without the premium ceiling, from 1 April 2025; the other conditions still apply | Exempt only if aggregate annual premium stays within ₹2.5 lakh; above it, a capital gain (12.5% on long-term equity gains above ₹1.25 lakh) |
| Indian tax on death | Exempt whatever the premium | Exempt | Exempt |
| Reporting | Schedule FA every year the holder is resident and ordinarily resident; the insurer’s country reports to India under CRS | Issued inside India’s IFSC; confirm the Schedule FA position with your CA | Domestic policy: no Schedule FA |
Position as at 1 November 2026. Minimum premiums are set by each insurer and are not a legal threshold. Detail and sources: PPLI vs ULIP and GIFT City life insurance.
India research, with its sources
Questions Indian families ask first
What is private placement life insurance?
Can a resident of India buy PPLI?
Is PPLI tax-free in India?
How is PPLI different from a ULIP?
What is the RNOR window?
What is FAST-DS 2026?
Can I buy a policy through PPLI.com?
Does a foreign life policy fit your family’s situation?
Five questions, a straight answer. Nothing is stored or sent; the answers stay in your browser. The result is not a review by your CA, but it tells you whether the conversation is worth having.
Written for Indian private wealth
NRIs and returning NRIs
Resident families with NRI members
CAs, private bankers and family offices
Sources and authorities
- FEMA 12(R)/2015-RB, Foreign Exchange Management (Insurance) Regulations, 2015; RBI Master Direction, Liberalised Remittance Scheme.
- Income-tax Act 1961, section 10(10D); sections 5, 6, 56(2)(xiii), 206C(1G); Schedule FA; Income-tax Act 2025.
- Memorandum to the Finance Bill 2025; Finance Act 2026 and the FAST-DS Rules 2026 (G.S.R. 732E of 14 August 2026) via KPMG (secondary).
- Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015; CBDT Guidance Note on FATCA and CRS; IFSCA (Registration of Insurance Business) Regulations 2021; IRDAI policyholder portal on ULIPs.
Ask a research question
Editorial standards